The deck is an investor presentation for WaFd's proposed merger with EverBank, dated September 7, 2026. It opens with a title slide and then a long forward-looking statements disclaimer and a note on presenters, followed by a transaction overview that sets out the combined bank's scale, multi-channel model and key deal terms such as the 100% stock structure, ownership split and anticipated 1Q'27 close. The middle sections cover the financial rationale, including EPS accretion, cost synergies, integration timeline, capital and liquidity, credit quality, and value creation scenarios based on price-to-tangible-book comparisons. Standalone profiles of EverBank's regional, national and digital channels, its deposit franchise and its management team follow in the main body. The appendix holds detailed channel descriptions, loan and deposit mix, non-depository and commercial real estate exposure, tangible book value and goodwill reconciliations, and the EPS accretion calculation. The deck ends with a closing slide reading Stronger Together. Several slides, including the channel mix and purchase accounting pages, show how complex financial data is laid out for an investor audience.
Slides worth studying
Questions about this deck
What are the key transaction details in the WaFd, Inc. and EverBank Financial Corp investor deck?
Slide 9 says the deal is 100% common stock consideration, with an ownership split of 59.2% EverBank and 40.8% WaFd. Slide 9 also gives an anticipated closing in 1Q'27.
What EPS accretion and return figures does the WaFd, Inc. and EverBank Financial Corp deck show?
Slide 7 shows ~29% 2027E EPS accretion and 15%+ 2027E ROATCE, both based on fully-synergized profitability metrics. Slide 7 also lists a 2.0 years TBV earnback period.
How large is the combined franchise in the WaFd, Inc. and EverBank Financial Corp presentation?
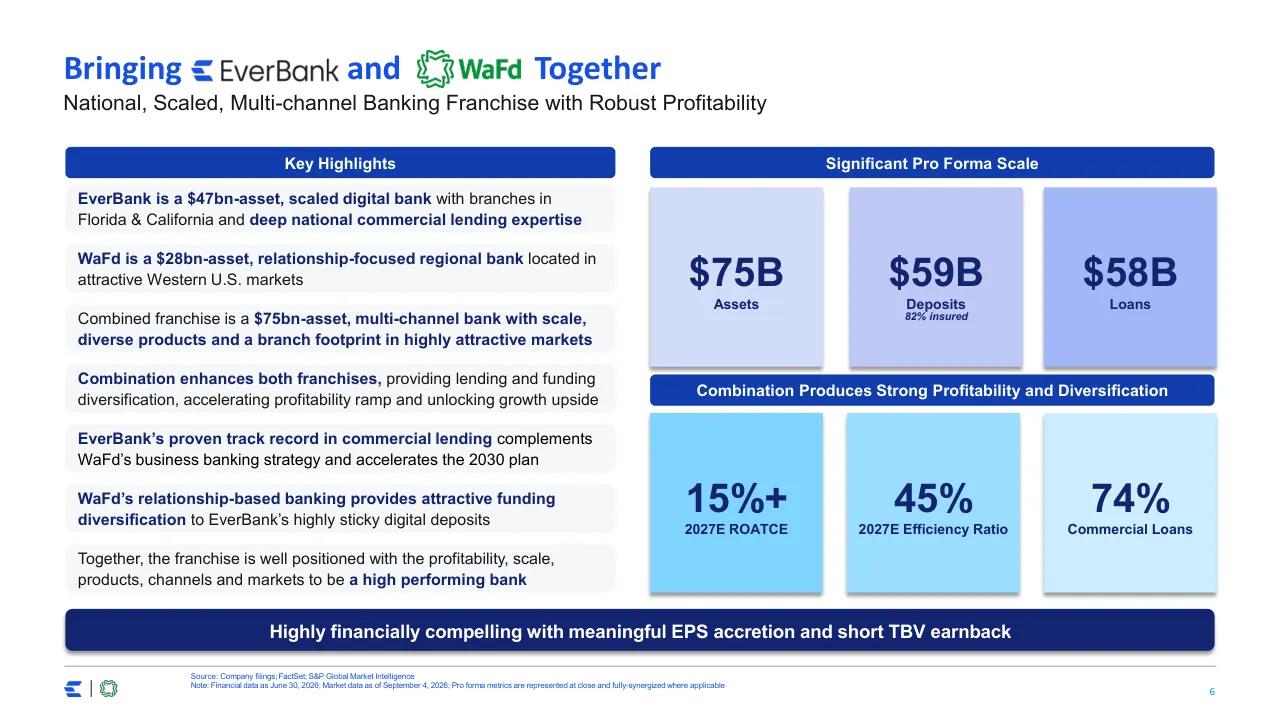
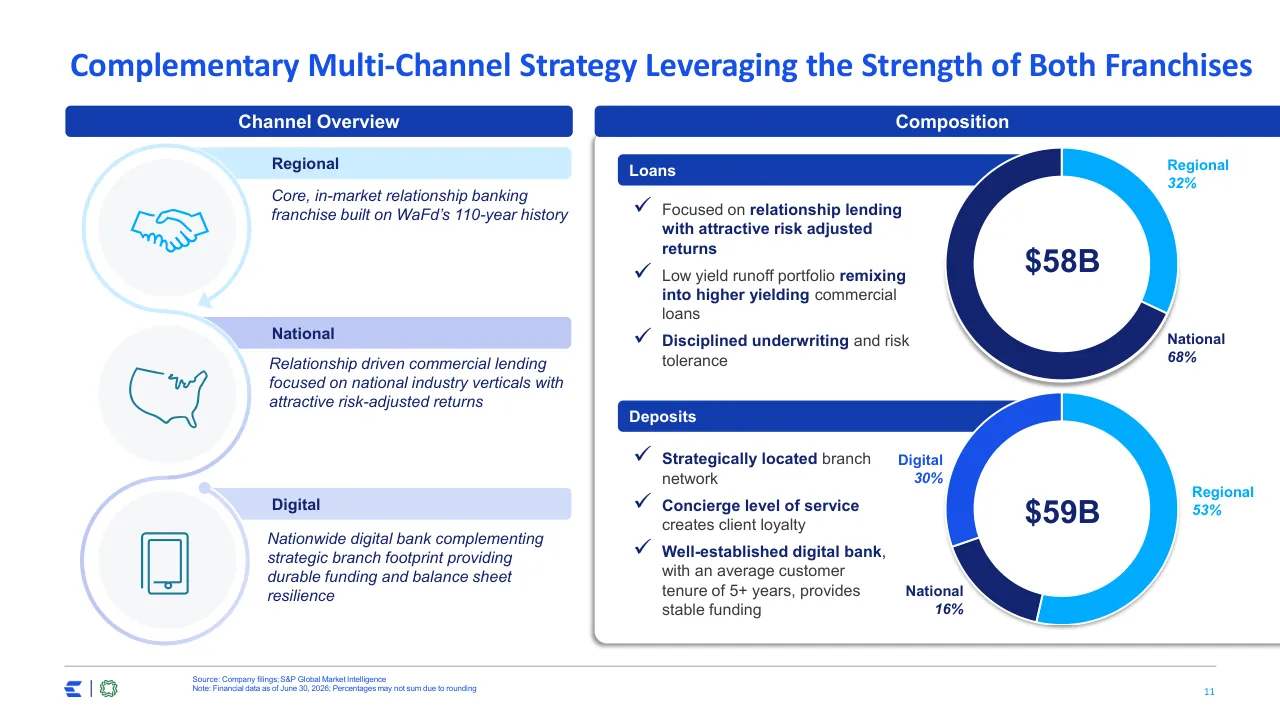
Slide 6 describes the combined franchise as a $75bn-asset, multi-channel bank with $59bn in deposits, 82% of which are insured, and $58bn in loans. Slide 6 also notes that financial data is as of June 30, 2026.
How many slides does the WaFd, Inc. and EverBank Financial Corp deck have and how is it organized?
The deck has 43 pages. Slide 2 is the forward-looking information statement, slide 4 introduces today's presenters, and slide 14 covers senior management with the board of directors.
Details
Review score: 7 out of 10, Effective
Presentation quality, judged with the SlideDeck Co review heuristic. Ask, evidence and idea merit are not rated here.
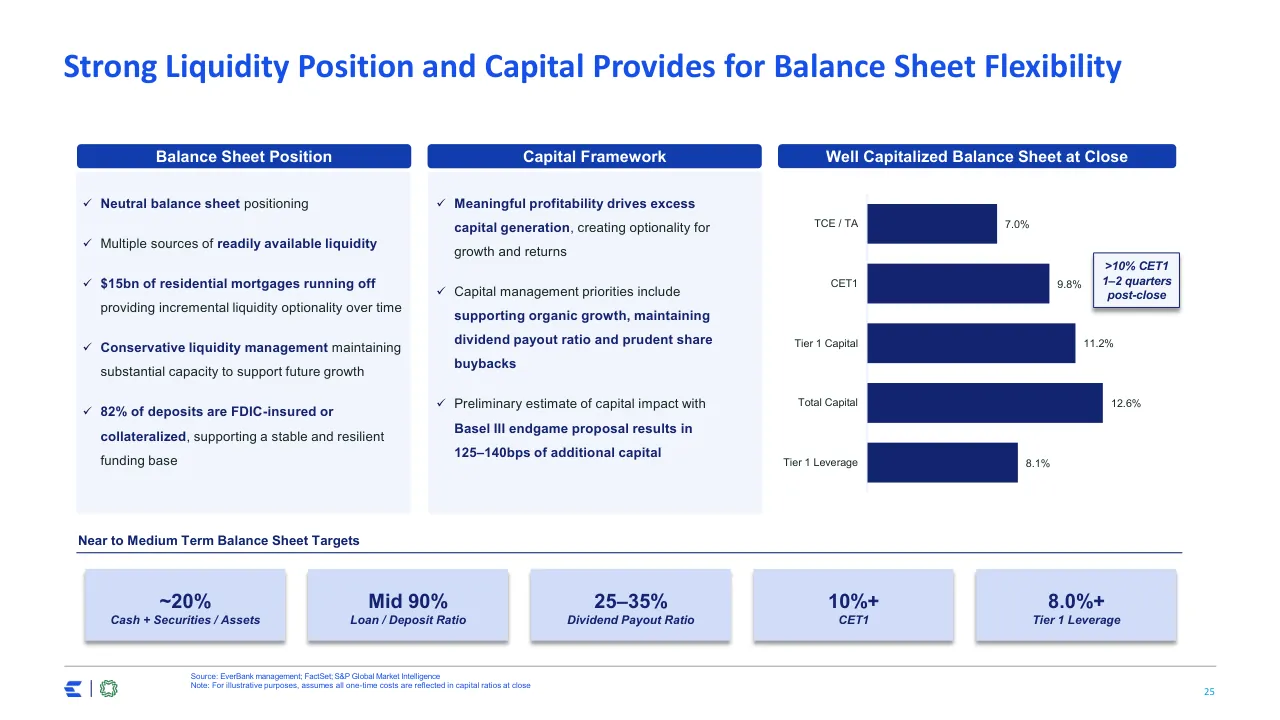
The deck has a clear route for an investor audience: transaction overview, financial rationale, value creation, standalone EverBank, then an appendix, with section dividers and a consistent blue-and-green identity and header bars. Slides 6, 11 and 25 show disciplined execution, with large key numbers, readable bars and donuts, and clear takeaways. The weaknesses are consequential: many slides (7, 9, 12, 16, 18, 22, 24, 26, 36, 41, 42) pack in tiny text and charts, the footnotes are nearly unreadable, and several titles are topic labels or generic claims, which makes the page-to-page argument harder to follow. Slide 11 repeats the loans and deposits donuts with a decorative icon column and uneven white space, and slide 27 mixes busy logos and checklists.
Worth keeping: Keep the consistent header-bar system, the large-number KPI tiles on slides 6 and 25, the blue-green palette, and the clear section dividers and sequence from overview to rationale to appendix.
Most useful repair: Cut the density on the pages with tiny text (slides 7, 12, 16, 18, 22, 24, 36, 41, 42) by splitting them or enlarging the key figures, and raise the footnotes to a legible size.
What would change the score: Rewrite the topic-label titles (for example slides 19, 21, 26, 30 and 33 to 35) as takeaways, and trim the legal pages on slides 2 and 3 to a short summary with the full text moved to the end.
Confidence high. 43 of 43 pages inspected on contact sheets, 4 at readable size. Reviewed 2026-11-08. Model-assisted review (claude-sonnet-5-5).
Full text of the slides (43 slides)
Every slide's words and a description of its charts and images, so the deck can be searched and rebuilt. Also available as Markdown.
Slide 1
EverBank + WaFd
Stronger Together
September 7, 2026
1
Visuals: Full-bleed background illustration of flowing, translucent ribbons with fine parallel line texture. Blue ribbons (royal blue #1565D8 to pale blue #CFE0F5) sweep from the top-left corner diagonally down toward the centre-right. Green ribbons (#2E9A3E to pale green #CDE8D0) sweep from the centre to the bottom-right corner and cross the blue ones. The two bundles meet and fade into near-white around the middle. Top right: EverBank logo, a blue (#1F4FE0) stacked chevron/E mark followed by the wordmark 'EverBank' in dark charcoal sans-serif, then a thin light-grey vertical divider and the WaFd logo, an outlined green scalloped square emblem with bold green 'WaFd' wordmark. Small slide number '1' at the bottom right.
Slide 2
Statement Regarding Forward-looking Information
This communication contains certain “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995, Section 27A of the Securities Act of 1933, as amended (the “Securities Act”), and Section 21E of the Securities Exchange Act of 1934, as amended (the “Exchange Act”) with respect to the beliefs, plans, goals, expectations and estimates of WaFd, Inc. (“WaFd”) and EverBank Financial Corp (“EverBank”). Forward-looking statements are not a representation of historical information, but instead pertain to future operations, strategies, financial results or other developments. The words “believe,” “expect,” “anticipate,” “intend,” “target,” “plan,” “estimate,” “should,” “likely,” “will,” “going forward” and other expressions that indicate future events and trends identify forward-looking statements.
Forward-looking statements are necessarily based upon estimates and assumptions that are inherently subject to significant business, operational, economic and competitive uncertainties and contingencies, many of which are beyond the control of WaFd and EverBank, and many of which, with respect to future business decisions and actions, are subject to change and which could cause actual results to differ materially from those contemplated or implied by forward-looking statements or historical performance. Examples of uncertainties and contingencies include factors previously disclosed in WaFd’s reports filed with the U.S. Securities and Exchange Commission (the “SEC”), as well as the following factors, among others: (i) the occurrence of any event, change or other circumstances that could give rise to the right of one or both of the parties to terminate the definitive merger agreement between WaFd and EverBank; (ii) the outcome of any legal proceedings that may be instituted against WaFd or EverBank, including potential litigation that may be instituted against WaFd or its directors or officers related to the proposed transaction or the definitive merger agreement between WaFd and EverBank; (iii) the timing and completion of the transaction, including the possibility that the proposed transaction will not close when expected or at all because required regulatory, shareholder or other approvals are not received or other conditions to the closing are not satisfied on a timely basis or at all, or are obtained subject to conditions that are not anticipated; (iv) the risk that any announcements relating to the proposed combination could have adverse effects on the market price of the common stock of WaFd; (v) the possibility that the anticipated benefits of the transaction will not be realized when expected or at all, including as a result of the impact of, or problems arising from, the integration of the two companies or as a result of the strength of the economy and competitive factors in the areas where WaFd and EverBank do business; (vi) certain restrictions during the pendency of the merger that may impact the parties’ ability to pursue certain business opportunities or strategic transactions; (vii) the possibility that the transaction may be more expensive to complete than anticipated, including as a result of unexpected factors or events; (viii) diversion of management’s attention from ongoing business operations and opportunities; (ix) reputational risk and potential adverse reactions or changes to business or employee relationships, including those resulting from the announcement or completion of the transaction; (x) WaFd’s and EverBank’s success in executing their respective business plans and strategies and managing the risks involved in the foregoing; (xi) currency and interest rate fluctuations; (xii) success of hedging activities; (xiii) material adverse changes in economic and industry conditions, including the availability of short and long-term financing; (xiv) general competitive, economic, political and market conditions; (xv) changes in asset quality and credit risk; (xvi) the inability to sustain revenue and earnings growth; (xvii) inflation; (xviii) customer borrowing, repayment, investment and deposit practices; (xix) the impact, extent and timing of technological changes; (xx) capital management activities; (xxi) other actions of the Board of Governors of the Federal Reserve System, the Office of the Comptroller of the Currency and the State of Washington; (xxii) legislative and regulatory actions and reforms; and (xxiii) other factors that may affect future results of WaFd and EverBank.
We caution that the foregoing list of important factors that may affect future results is not exhaustive. Additional factors that could cause results to differ materially from those contemplated by forward-looking statements can be found in WaFd’s Annual Report on Form 10-K for the fiscal year ended September 30, 2025, and in its subsequent Quarterly Reports on Form 10-Q filed with the SEC and available in the “Investor Relations” section of WaFd’s website, www.wafdbank.com/about-us/investor-relations, under the heading “SEC Filings” and in other documents WaFd files with the SEC (available at www.sec.gov). All such factors, as well as other uncertainties and potential events, and the inherent uncertainty of forward-looking statements, should be considered carefully when making decisions with respect to WaFd and EverBank.
Any forward-looking statements contained in this document represent the views of WaFd and EverBank only as of the date hereof and are presented for the purpose of assisting their respective shareholders and analysts in understanding WaFd’s and EverBank’s financial position, objectives and priorities and anticipated financial performance as at and for the periods ended on the dates presented, and may not be appropriate for other purposes. Neither WaFd nor EverBank undertakes to update any forward-looking statements, whether written or oral, that may be made from time to time by or on its behalf, except as required under applicable securities legislation.
2
Visuals: A thin light-grey horizontal rule spans from x≈5% to 95% at y≈92.5%. At bottom left (x≈5–9.3%, y≈94–97%) are two small logos separated by a thin vertical divider: a blue stylised 'E' mark made of three slanted bars (EverBank), then a thin dark vertical line, then a small green circular wreath-like emblem (WaFd). No charts or images.
Slide 3
Important Other Information
In connection with the proposed transaction, WaFd intends to file relevant materials with the SEC, including a proxy statement on Schedule 14A. Promptly after filing its definitive proxy statement with the SEC, WaFd will mail the definitive proxy statement to each shareholder entitled to vote at the meeting relating to the proposed transaction.
This communication does not constitute an offer to sell or a solicitation of an offer to buy any securities or a solicitation of any vote or approval. SHAREHOLDERS OF WAFD ARE URGED TO READ, WHEN AVAILABLE, ALL RELEVANT DOCUMENTS (INCLUDING ANY AMENDMENTS OR SUPPLEMENTS THERETO) FILED WITH THE SEC, INCLUDING WAFD’S PROXY STATEMENT, BECAUSE THEY WILL CONTAIN IMPORTANT INFORMATION ABOUT WAFD AND THE PROPOSED TRANSACTION.
Investors and shareholders of WaFd will be able to obtain a free copy of the proxy statement as well as other relevant documents filed with the SEC without charge at the SEC’s website (http://www.sec.gov). Copies of the proxy statement and the filings with the SEC that will be incorporated by reference in the proxy statement can also be obtained, without charge, by directing a request to Brad Goode, WaFd, Inc., 425 Pike Street, Seattle, Washington 98101, telephone (206) 626-8178.
Participants in the Solicitation
WaFd, EverBank and certain of WaFd’s directors and executive officers may be deemed to be participants in the solicitation of proxies in respect of the proposed transaction under the rules of the SEC. Information regarding WaFd’s directors and executive officers is available in the proxy statement for its 2026 annual meeting of shareholders, which was filed with the SEC, and certain of its Current Reports on Form 8-K. Other information regarding the participants in the proxy solicitation and a description of their direct and indirect interests, by security holdings or otherwise, will be contained in the proxy statement and other relevant materials to be filed with the SEC when they become available. Free copies of these documents, when available, may be obtained as described in the preceding paragraph.
Non-GAAP Financial Measures
This communication contains certain non-GAAP financial measures that are not in accordance with U.S. generally accepted accounting principles (GAAP). WaFd uses certain non-GAAP financial measures to provide meaningful, supplemental information regarding its operational results and to enhance investors’ overall understanding of WaFd’s financial performance. The limitations associated with non-GAAP financial measures include the risk that persons might disagree as to the appropriateness of items comprising these measures and that different companies might calculate these measures differently. These disclosures should not be considered an alternative to WaFd’s GAAP results.
3
Visuals: Thin light grey horizontal line across the bottom at about y 92.5%. Bottom-left footer has the EverBank logo mark (blue stylised E of stacked bars), a thin vertical divider line, and a small green outlined WaFd emblem (a scalloped/starburst circle shape).
Slide 4
Today’s Presenters
EverBank
WaFd
Greg Seibly
Chief Executive Officer
Brent Beardall
President, Chief Executive Officer
Pat Rusnak
Chief Financial Officer,
Executive Vice President
Kelli Holz
Chief Financial Officer,
Executive Vice President
4
Visuals: Four circular headshot photos with coloured ring borders. Greg Seibly: older man with light/reddish hair, dark navy suit, white shirt, light blue tie, bright office background, blue ring. Pat Rusnak: older man with glasses, brown tweed jacket, light blue shirt, red striped tie, light office background, blue ring. Brent Beardall: smiling man with short brown hair, navy suit, patterned gold tie, blue studio backdrop, green ring. Kelli Holz: smiling woman with wavy brown shoulder-length hair, dark patterned jacket, blue backdrop, green ring. EverBank logo: blue stacked-bar E mark followed by dark grey 'EverBank' wordmark. WaFd logo: green outlined scalloped star/seal mark followed by bold green 'WaFd' wordmark. Footer: small blue EverBank mark, thin vertical divider, small green WaFd mark. Thin grey horizontal line across the slide above the footer.
Slide 5
Transaction Overview
5
Visuals: Full-bleed abstract illustration of flowing, translucent ribbon-like waves. Blue ribbons (royal blue #1B6AD6 to pale blue #DCE8F7) sweep from the top-left corner diagonally down toward the centre-right. Fine parallel hairlines fan out along the lower edge of the blue band. The ribbons fade to white around the middle, then green ribbons (#2E9A3E to pale green #D6EBD6) continue to the bottom-right corner. Faint grey-white curved shapes sit at the right edge. The rest is near-white and open. There are no logos or icons.
Slide 6
Bringing EverBank and WaFd Together
National, Scaled, Multi-channel Banking Franchise with Robust Profitability
Key Highlights
EverBank is a $47bn-asset, scaled digital bank with branches in Florida & California and deep national commercial lending expertise
WaFd is a $28bn-asset, relationship-focused regional bank located in attractive Western U.S. markets
Combined franchise is a $75bn-asset, multi-channel bank with scale, diverse products and a branch footprint in highly attractive markets
Combination enhances both franchises, providing lending and funding diversification, accelerating profitability ramp and unlocking growth upside
EverBank’s proven track record in commercial lending complements WaFd’s business banking strategy and accelerates the 2030 plan
WaFd’s relationship-based banking provides attractive funding diversification to EverBank’s highly sticky digital deposits
Together, the franchise is well positioned with the profitability, scale, products, channels and markets to be a high performing bank
Significant Pro Forma Scale
$75B
Assets
$59B
Deposits
82% insured
$58B
Loans
Combination Produces Strong Profitability and Diversification
15%+
2027E ROATCE
45%
2027E Efficiency Ratio
74%
Commercial Loans
Highly financially compelling with meaningful EPS accretion and short TBV earnback
Source: Company filings; FactSet; S&P Global Market Intelligence
Note: Financial data as June 30, 2026; Market data as of September 4, 2026; Pro forma metrics are represented at close and fully-synergized where applicable
6
Visuals: EverBank logo (blue stacked-chevron mark with 'EverBank' in dark grey) inline in the title between 'Bringing' and 'and'. WaFd logo (green outlined starburst mark with green bold 'WaFd') inline between 'and' and 'Together'. Top stat tiles with soft drop shadows in graduated periwinkle blues, light to darker left to right. Bottom stat tiles with soft drop shadows in sky blue, light cyan on the right. Footer has a small blue EverBank chevron icon, a thin vertical divider and a small green WaFd icon. A thin grey horizontal rule runs above the footer. Navy banner has a subtle shadow and rounded corners.
Slide 7
A Merger That is Financially Compelling
Attractive Pricing Drives Strong EPS Accretion with Minimal Tangible Book Value Dilution and Short Earnback
Highly Compelling Financial Returns
Attractive Pricing
Highly accretive to / WaFd EPS with robust / earnings power and / profitability
~29%
2027E EPS accretion (1)
15%+
2027E ROATCE (1)
$865M+
Run-rate earnings (2)
2027 Price / Earnings
10.8x
8.9x
7.2x
synergized
Enhanced profitability / drives short TBV / earnback period and / excess capital / generation
(8.6%)
TBV per share dilution
2.0 years
TBV earnback period (3)
~90bps+
Annual CET1 generation (4)
Price / TBVPS
1.2x
1.1x
Well-capitalized / pro forma / balance sheet
9.8%
CET1
8.1%
Tier 1 leverage
12.6%
Total capital
~90% pay-to-trade ratio
Enhanced ROATCE and EPS accretion support ~25–45% upside to current share price (5)
Source: Company filings; FactSet; S&P Global Market Intelligence
Notes: Financial data as of June 30, 2026; Market data as of September 4, 2026
1. Based on fully-synergized profitability metrics on a calendar year basis; 2. Represents net income to common; 3. TBV earnback period reflects crossover method; 4. Run rate organic CET1 generation before dividends; 5. See pages 29 and 30
7
Visuals: Two small bar charts in the right column. Chart 1, '2027 Price / Earnings': three bars on a black baseline, green (10.8x, tallest), navy (8.9x) and bright blue (7.2x), with value labels above each. Icons under the bars: green star-shaped WaFd logo under the first bar, blue stacked-chevron logo under the second and third bars, with the italic caption 'synergized' under the third. Chart 2, 'Price / TBVPS': two bars on a black baseline, green (1.2x) and navy (1.1x), with the same logos under each and the caption '~90% pay-to-trade ratio'. Bottom-left footer has the blue chevron logo, a thin vertical divider and the green star logo. The rows are separated by thin grey horizontal lines. The label cells have a thick navy vertical bar on their right edge. The bottom banner has a soft shadow.
Slide 8
EverBank + WaFd : Stronger Together
Bringing Together Complementary Institutions to Create a Highly Profitable and High-Growth Franchise
1
Multi-channel, relationship-driven strategy pairing a regional bank with a national, digital and commercial lending franchise
2
Strategically located in attractive, high-growth markets, serving clients locally and nationally
3
Scale, funding and asset deployment strategy to navigate a rapidly evolving banking environment
EverBank
+ WaFd
4
Strong EPS accretion, return profile, and earnings power support robust growth and capital return
5
Efficient cost structure and flexible funding model enable outperformance across economic cycles
6
Experienced management team with significant integration experience and deep local and national expertise
7
Scarcity value underpinned by diverse business model, robust profitability, and scale in attractive markets
8
Visuals: Concentric circular arcs on the left, cut off by the left edge: outermost royal blue #1751E8, then navy #14246E, then cyan #00AEEF, then green #00A040 around a light grey #F2F2F2 half-disc. Inside the disc: EverBank logo (blue stacked-bars mark with dark grey wordmark) and below it a grey plus sign and the green WaFd logo with a seal mark. Seven white circles with thick blue outlines, numbered 1-7, are placed along the arcs, forming a left-bulging curve with 1 and 7 farthest left and 4 farthest right. Seven horizontal bands with a pale blue-lavender gradient that fades to white on the right. The title carries the EverBank logo, a blue plus, and the green WaFd logo. The footer has a small blue EverBank mark, a thin vertical divider and a small green WaFd seal icon.
Slide 9
Key Transaction Details
Structure
WaFd, Inc. issues shares to EverBank Financial Corp stockholders
WaFd, Inc. will remain a publicly traded bank holding company, renamed EverBank Financial Corp under a new ticker – EVBK
WaFd will be the legal acquiror and EverBank will be the accounting acquiror (WaFd’s balance sheet will be subject to fair value accounting)
EverBank Financial Corp will be regulated by the Federal Reserve and EverBank, N.A. by the OCC
Consideration
100% common stock consideration
WaFd will issue 103.1mm shares(1) (107.7mm inclusive of options) in connection with the transaction
Pro forma shares: 177.1mm basic | 182.0mm diluted
Ownership split: 59.2% EverBank / 40.8% WaFd
Brand
Holding company
Regional
National
Digital
EverBank
West region: WaFd
CA / FL: EverBank
EverBank
EB Direct (pending)
Headquarters
Holding company: Bellevue, WA | Bank: Jacksonville, FL
Board of Directors
7 EverBank / 6 WaFd Directors
Chairman: Robert Radway | Directors include Greg Seibly and Brent Beardall
Leadership:
Chief Executive Officer: Greg Seibly
President: Brent Beardall
Conditions / approvals
Subject to receipt of WaFd shareholder approval
Approval of EverBank stockholders has been obtained
Subject to customary regulatory approvals
EverBank stockholders entitled to customary registration rights and have agreed to a phased lock up schedule over 12 months post closing(2)
Anticipated closing in 1Q’27
Source: Company filings; FactSet; S&P Global Market Intelligence
Notes:
1. Number of WaFd shares to be issued at closing will depend on the number of fully diluted shares of WaFd as of closing (calculated using the treasury stock method based on the 10-day VWAP of the WaFd shares prior to closing) to target an ownership split of 59.2% to EverBank and 40.8% to WaFd; includes additional dilutive commitments; 2. Four-period lock up beginning at closing, with shares released 10% / 10% / 40% / 40% after 30 days, 90 days, 180 days and 12 months, respectively
9
Visuals: Seven pale blue label cells (#E4EAFC) with a thick dark navy vertical bar at each cell's right edge. Four dark blue rounded header bars in the Brand row (Holding company, Regional, National, Digital) with white bold text. Blue circular bullets before each item. Thin grey horizontal divider lines between rows and above the footer. Two small logos at the bottom left: a blue stylised 'E' EverBank mark, then a thin vertical divider, then a green circular wreath-style WaFd mark.
Slide 10
Scaled Presence in Highly Attractive Markets Creates Scarcity Value
Strategically Located in High-Growth and Wealthy Markets
Sizable Growth Opportunity
(212)
(42)
Seattle
Olympia
WA
MT
Portland
Salem
Boise
ID
OR
WY
Salt Lake City
UT
Carson City
NV
CO
San Francisco
San Jose
CA
Las Vegas
Santa Fe
AZ
NM
Los Angeles
Long Beach
Phoenix
San Diego
Mesa
254 total branches
Texas
Ft. Worth
Dallas
TX
Austin
Florida
Jacksonville
FL
Tampa
West Palm Beach
Naples
Miami
4th Largest
Bank Holding Company
Headquartered in Western U.S. (1)
8 of Top 15
MSAs by Population
6 of Top 10
Growth States(2)
$105k HHI
vs. $87k
National Average(3)
24 MSAs
with over 500k population
3 of Top 5
MSAs with Most
Middle Market Businesses(4)
Source: S&P Global Market Intelligence; United States Census Bureau
Note:
1. Includes banks with total assets less than $1 trillion; 2. As defined by population growth rate (2020–2026); 3. Company household income calculated as weighted average based on deposits by county, excludes EverBank headquarters; 4. Middle market businesses defined as companies with 100-499 employees
10
Visuals: Left: a map of the western US (WA, OR, CA, NV, ID, MT, WY, UT, CO, AZ, NM) filled pale blue #D1DCFA, with MT, WY and CO in grey #DDDCDB. Green dots mark the 212 branches of one bank and blue dots mark the 42 EverBank branches. Green dots are concentrated around Seattle, Portland, Salem, Boise and Phoenix and scattered across the interior states. Blue dots cluster around San Francisco/San Jose, Los Angeles/Long Beach and in Nevada. A legend at top-left shows a green dot with a green star-like logo (212) and a blue dot with a blue stacked E logo (42). Middle: a white panel with a subtle shadow holding two circular insets with blue (#1751E8) outlines. The Texas inset shows a pale blue Texas map with a few green dots near Ft. Worth/Dallas and Austin. The Florida inset shows a pale blue Florida map with blue dots at Jacksonville, Tampa, Naples, West Palm Beach and Miami. Right: six pale blue tiles (#D1DCFA) with soft drop shadows in a 2x3 grid. Footer: blue stacked E logo, a thin vertical divider and a green star-like logo at bottom-left, and a thin grey horizontal rule above the footer.
Slide 11
Complementary Multi-Channel Strategy Leveraging the Strength of Both Franchises
Channel Overview
Composition
Regional
Core, in-market relationship banking / franchise built on WaFd’s 110-year history
National
Relationship driven commercial lending / focused on national industry verticals with / attractive risk-adjusted returns
Digital
Nationwide digital bank complementing / strategic branch footprint providing / durable funding and balance sheet / resilience
Loans
Focused on relationship lending with attractive risk adjusted returns
Low yield runoff portfolio remixing into higher yielding commercial loans
Disciplined underwriting and risk tolerance
$58B
Regional
32%
National
68%
Deposits
Strategically located branch network
Concierge level of service creates client loyalty
Well-established digital bank, with an average customer tenure of 5+ years, provides stable funding
$59B
Digital
30%
Regional
53%
National
16%
Source: Company filings; S&P Global Market Intelligence
Note: Financial data as of June 30, 2026; Percentages may not sum due to rounding
11
Visuals: Left column: three light grey circular backgrounds (#F5F7F8) each with a large pale ring outline. Ring 1 is light blue (#CCEEFF) with an arrow tip pointing down-left toward the next ring; ring 2 is lavender; ring 3 is pale periwinkle with a small dot at its top. Icons: a light-blue line-art handshake (Regional), a teal line-art outline of the United States map (National), and a teal line-art tablet/phone device (Digital). Right panel: two donut charts with soft shadows and white centres. Loans donut ($58B): Regional 32% in bright blue (#00AAFF) on the upper right, National 68% in dark navy (#142571) for the rest. Deposits donut ($59B): Regional 53% bright blue (#00AAFF) on the right, Digital 30% royal blue (#1751E8) on the upper left, National 16% dark navy (#142571) at the bottom left. Dark blue header bars for Loans and Deposits are partially overlapped by the donuts. Dark navy checkmarks beside each bullet. Footer logos: a blue stylised E mark, a thin vertical divider, and a green outlined emblem.
Slide 12
Commercially Focused Bank with Diverse Deposit Funding – Unlocks Growth / and Earnings Potential
Lending
Deposits
Diversified National and Regional Lending Portfolio Underwritten with / Commercial Expertise
Multi-Faceted, Efficient Deposit Gathering Strategy
Consumer
CRE
Legacy runoff
Residential
12%
25%
16%
Multi-family
4%
7%
Corporate debt / finance
C&D
16%
11%
C&I(1)
Fund finance
6%
2%
Lender finance
Structured / mortgage finance
$58B / Total
Yield on loans: 5.60%(2)
74% Commercial
Other
11%
16%
Commercial direct / and specialty
43%
Financial / centers
$59B / Total
30%
Consumer / direct
Cost of deposits: 2.73%
82% FDIC-insured
Larger balance sheet enables greater growth
Reduces lending concentrations
Diverse, sticky funding supports lending growth
Source: Company filings; S&P Global Market Intelligence
Note: Financial data as of June 30, 2026; Percentages may not sum due to rounding
1. Includes EverBank Sterling loans allocated to C&I; 2. Includes accretion income
12
Visuals: Left: donut chart for the $58B lending portfolio with segments clockwise from the top: CRE 12% (bright blue #1751E8), Multi-family 16% (dark navy #142571), Corporate debt finance 7% (mid blue #0A82BE), Fund finance 11% (light sky blue #66CCFF), Lender finance 2% (very pale blue #99DDFF), Structured mortgage finance 6% (very dark teal #1F3B3B), C&I 16% (teal #68ADAD), C&D 4% (green #3CC878), Residential 25% (grey #B0B0B0), plus a tiny Consumer sliver at the top. A blue dashed arc with blue dot end markers runs around the commercial segments, from the top near Consumer round clockwise to C&D. A black dotted arc with black dot markers runs round the Residential/Legacy runoff segment on the upper left. Right: donut chart for the $59B deposits: Financial centers 43% (bright blue #1751E8), Consumer direct 30% (lavender #BFC9F4), Commercial direct and specialty 16% (pale blue #CCEEFF), Other 11% (grey-teal #9AC2C2). Centre text of each donut is bold italic blue. Four callout pills with white fill and blue dashed outlines. Three light-blue takeaway boxes with drop shadows. Footer logos: a blue stylised E mark, a thin vertical divider and a green outlined emblem. Thin grey horizontal rule above the footer.
Slide 13
Combination Accelerates WaFd’s Goals
CURRENT STRATEGY
EXPAND
COMMERCIAL
LENDING
~15% ROATCE
ENHANCE
DEPOSIT
FRANCHISE
Advances
evolution to a
commercial bank
64% → 74%
Commercial loans
Accelerates
profitability
journey
10% → 15%+
ROATCE
Enhances digital
capabilities and
enhances
funding flexibility
61% → 73%
Non-time deposits
Opportunity To Optimize The
Balance Sheet
Meaningful Cross-Sell
Opportunities
Source: Company filings; FactSet; S&P Global Market Intelligence
Note: Financial data as of June 30, 2026; Market data as of September 4, 2026; Pro forma metrics are represented at close and fully-synergized where applicable
13
Visuals: Venn diagram: two overlapping white circles with thick light-grey outlines, one above the other. The lens-shaped overlap is filled grey and labelled ~15% ROATCE. Three white circles with pale green outlines each contain a green check mark, overlapping the top-right corners of the cards. Footer logos: a blue stylised E mark, a thin vertical divider, and a green outlined emblem.
Slide 14
Senior Management with Deep Market Experience and Proven Track Record
Leadership Structure
BOARD OF DIRECTORS
7 EverBank
WaFd 6
Robert Radway
Chairman
MANAGEMENT TEAM
years of experience
Greg Seibly
Chief Executive Officer
>35 years
Brent Beardall
President
31 years
Pat Rusnak
Chief Financial Officer
>20 years
Seth Waller
Chief Credit Officer
30 years
Mercy Anne Martin
Chief Risk Officer
29 years
Mark Baum
General Counsel
26 years
Kim Robison
COO, Regional Banking
>35 years
Greg Seibly
Chief Executive Officer
Board Director
Union
FHLBank San Francisco
UMPQUA
STERLINGBANK
Bank of America
us bancorp
WELLS FARGO
Brent Beardall
President
Board Director
WaFd
25 years
Deloitte.
6 years
Senior Management Team Has Significant Integration Experience
Sterling
us bancorp
UnionBank
TIAA Bank
TIAA
UMPQUA
STERLINGBANK
WaFd
Luther Burbank
Combined Company Exhibits Culture of Excellence
5-Star
BauerFinancial Rating
Best Internet
Banks of 2025
Best-in-State Bank
Best Banks
Awarded “Superior”
5-star rating for competitive
rates and financial strength
Awarded Kiplinger’s
Best Internet Banks of
2025 Award
Recognized by Forbes
among America’s Best Banks
Recognized by Forbes among
America’s Best Banks
Source: Company filings
14
Visuals: Circular headshot photos of each executive (Greg Seibly, Brent Beardall, Robert Radway, Pat Rusnak, Seth Waller, Mercy Anne Martin, Mark Baum, Kim Robison) with blue or green ring borders. EverBank blue stacked-E logo and WaFd green logo are used as tags on cards. Past-employer logos: Union Bank, FHLBank San Francisco, Umpqua, Sterling Bank, Bank of America, U.S. Bancorp, Wells Fargo, Deloitte, WaFd, Sterling, TIAA Bank, TIAA, Luther Burbank. Award badges: BauerFinancial five-star gold column emblem, Kiplinger Best Banks 2024 badge, Forbes Best-in-State Banks 2025 black plaque, green Best Banks 2025 ribbon. Board bar: blue segment labelled 7 EverBank and green segment labelled WaFd 6. White cards with a light shadow.
Slide 15
Overview of Standalone EverBank
15
Visuals: Full-bleed abstract illustration of flowing translucent ribbon waves. Blue ribbons (from #0A6AD8 to pale #DCE8F7) sweep from the top-left corner and curve down toward the centre. Green ribbons (about #2E9A3E fading to pale #E3F1E3) sweep from the centre-right toward the bottom-right corner. Thin white and pale lines run along the ribbon edges, and fine striations show on the lower blue and green bands. Large areas of near-white (#F8F9FA) remain in the upper right and lower left. A faint grey-white curved band crosses the right edge.
Slide 16
EverBank at a Glance
The Premier, Multi-channel Specialty Commercial Bank With National Reach
Growth-Oriented, Profitability Focused
Digitally Led, Efficient Deposit Gathering Strategy
Relationship Driven, National Commercial Lending
$46.7B
Assets
$37.7B
Deposits
$37.1B
Loans & Leases
$9.1B
Cash & Securities
53%
Adj. Efficiency Ratio (1) (2)
2.59%
NIM (2)
0.45%
Adj. NPAs / Assets (4)
0.02%
NCOs / Avg. Loans
Growth
Profitability
Loans ($B)
ROAA
CAGR: 12%
$26
$37
2023
2Q26
0.28%
0.59%
0.71%
0.96%
2023
2024
2025
YTD 2026
~500,000
Deposit Accounts
87%
FDIC-Insured
5+ years
Average Tenure (3)
$55k
Avg. Account Size
Sweeps & Other
Financial Centers
Commercial & Specialty
Consumer Digital
13%
27%
13%
47%
$38B
Since 2023, deposits grew 38% (11% CAGR)
Loan Mix
Origination Mix
Commercial
Commercial Real Estate
Residential (5)
57%
23%
20%
68%
32%
2Q26
2Q26
Core Lending Lines
Structured Real Estate
Lender Finance
CRE Bridge
Fund Finance
Multi-family
Corporate Debt Finance
C&I (6)
Structured Mortgage Finance
Residential Mortgage
Legacy Comm. Real Estate
Equipment Lending
EverBank
Legacy Runoff
Since 2023, loans grew 41%, while yields increased by 56 bps
Source: Company filings, EverBank management, S&P Global Market Intelligence
Notes: Financial data as of June 30, 2026; Percentages may not sum due to rounding
1. Adjusted for one-time costs; 2.Reflects QTD; 3. Reflects tenure within digital bank; 4. Excludes government-insured pool buyout loans for which payment is insured by the government; 5. Residential includes consumer loans, HELOCs and EBOs; 6. C&I includes Life Lending, Public Finance and SBA lending
16
Visuals: Left: two bar charts in navy. Loans ($B) has two bars, 2023 $26 and 2Q26 $37, with a bracket arrow labelled CAGR: 12%. ROAA has four bars of increasing height: 2023 0.28%, 2024 0.59%, 2025 0.71%, YTD 2026 0.96%. Two periwinkle label buttons, Growth and Profitability, sit above them. Middle: donut chart with centre label $38B, segments Financial Centers 27% (bright blue), Consumer Digital 47% (light periwinkle), Commercial & Specialty 13% (light cyan), Sweeps & Other 13% (light grey). Right: two stacked bars. Loan Mix 2Q26: Commercial 57% navy, Commercial Real Estate 23% cyan, Residential 20% blue. Origination Mix 2Q26: 68% navy, 32% bright cyan. Below them is a ring diagram of blue wedges with white labels (Structured Real Estate, Lender Finance, CRE Bridge, Fund Finance, Multi-family, Corporate Debt Finance, C&I, Structured Mortgage Finance, Equipment Lending) and pale wedges for Residential Mortgage and Legacy Comm. Real Estate. A green dotted arc with green end dots surrounds the core lending wedges, and a pale dotted arc marks Legacy Runoff. The EverBank logo is in the centre of the ring. Footer has the small blue EverBank logo mark and a green outline emblem separated by a thin vertical line.
Slide 17
Digital Deposits Provide a Stable, Efficient and Scalable Source of Funding
Digital Bank Pioneers with Long-Term Relationships
Demonstrated Stickiness Through Macro Stress
~370k
Total Accounts
$17.7B
Deposits
$48k
Avg. Account Size
1998
Digital Bank launch
5+ yrs
Avg. tenure
<1.00%
Monthly Attrition
QoQ Deposit Growth During the 2023 Liquidity Panic (1)
1Q23
2Q23
1%
2%
(5%)
(3%)
(3%)
(2%)
(1%)
1%
Bottom quartile
Middle quartile
Top quartile
EverBank
KRX (2)
Designed to deliver stable, durable funding
Ability to quickly scale to fund loan growth
Highly efficient with meaningful operating leverage
Data-driven, targeted marketing approach creates cost effective acquisition
During the bank liquidity panic (SVB), EverBank grew digital deposits while most mid-sized banks experienced deposit outflows
Source: Company filings, EverBank management, S&P Global Market Intelligence
Notes: Financial data as of June 30, 2026
1. EverBank reflects growth of direct bank deposits, KRX quartiles reflect growth in total deposits excluding brokered and reciprocal deposits; 2. Represents the Nasdaq Regional Banking Index
17
Visuals: Bar chart, 'QoQ Deposit Growth During the 2023 Liquidity Panic', clustered columns of 1Q23 (light blue #7497F1) and 2Q23 (dark navy #142571) around a zero baseline. Legend top right with square swatches. EverBank (highlighted in a light blue rounded panel with blue outline and shadow): 1Q23 about 1% (above zero), 2Q23 2%. KRX quartiles in a grey rounded panel: Bottom quartile 1Q23 (5%), 2Q23 (3%); Middle quartile 1Q23 (3%), 2Q23 (2%); Top quartile 1Q23 (1%), 2Q23 1%. KRX label with a thin navy rule above it. EverBank logo (blue stacked-chevron icon plus 'EverBank' wordmark) at the bottom of the highlighted panel. Six stat tiles with soft shadows: top row pale lavender, bottom row light cyan shades. Four navy checkmark icons beside bullets. Footer has a small blue EverBank icon, a vertical divider and a green circular emblem.
Slide 18
EverBank’s Management Team Has Successfully Transitioned a Thrift to an
Efficient Commercial Bank
History of EverBank
Actions Taken Under New Leadership
Results Under New Leadership
1994
Founded by Alliance
Capital Partners
Received Bank charter
Expanded bank strategy
Added diversified asset generation channels
Expanded branches in strategic locations
outside Jacksonville
2012
Initial public offering of EverBank
Business optimization & organic growth
2017
Sale to TIAA completed
Servicing TIAA participants / exit of non-
strategic verticals, including mortgage banking
2023
TIAA sold to private investors
and rebranded EverBank
Today
Built an efficient, profitable and
high-growth commercial bank
FULL COMMERCIAL BANK
✓ Changed its charter to a National Bank from a Thrift
✓ Expanded deposit client focus beyond TIAA customers
✓ Shifted focus to higher-yielding commercial loans
✓ Mortgage runoff supports the shift toward higher-
yielding commercial lending
✓ Addition of 9 new lending verticals
DEPOSIT AND FUNDING OPTIMIZATION
✓ Accelerated de novo branch strategy to
complement digital bank
✓ Reduced wholesale funding
✓ Significantly increased core deposit base
EXECUTION OF VALUE ENHANCING
ACQUISITIONS
✓ Acquired Primis Life Premium Finance
✓ Acquired Sterling Bank
IMPROVED ASSET MIX – LOAN PORTFOLIO MIX
Residential (1)
CRE
Asset-Backed Lending
Consumer
Structured Mortgage
Equipment Financing
C&I
13%
2%
12%
18%
34%
4%
11%
10%
$26B
$37B
23%
16%
26%
31%
2023
2Q26
RIGHT-SIZED EXPENSE BASE – NIX / ASSETS
NIX($M)
$760 (2)
$693
2.09%
1.49%
2023
2Q26
ENHANCED PROFITABILITY – ROAA
NI($M) (3)
$89
89% CAGR
$398
0.96%
0.28%
2023
YTD 2026
Source: Company filings, EverBank management
Notes: Financial data as of June 30, 2026; Quarterly data reflects annualized figures; Percentages may not sum due to rounding
1. Residential excludes consumer loans, HELOCs and EBOs; 2. Includes shared services; 3. Net income to common
18
Visuals: Left: a grey vertical arrow band pointing down with a tip near the bottom, with grey year boxes (1994, 2012, 2017), a navy 2023 box and a bright blue Today box, each with a white border and shadow. Black dot bullets sit beside the italic timeline items. A lavender-grey translucent bar extends from the 2023 box to the middle column, with a tapering lavender-grey wedge joining the timeline to the cards. Middle: three light grey (#F5F7F8) rounded cards with shadows, each with a thick navy vertical bar at its left edge. Right: two donut charts for 2023 ($26B) and 2Q26 ($37B) with a grey right arrow between them. Legend colours: Residential bright blue, CRE navy, Asset-Backed Lending teal blue, Consumer lavender, Structured Mortgage cyan, Equipment Financing dark green-grey, C&I green. 2023 slices: 34% blue, 26% navy, 16% teal, 11% cyan, 13% dark green. 2Q26 slices: 18% blue, 23% navy, 31% teal, 10% cyan, 4% green, 12% dark green, 2% lavender. Below, a bar chart of NIX/Assets with navy bars: 2023 2.09% and 2Q26 1.49%, with pill labels NIX($M) $760(2) and $693. Then a ROAA bar chart: 2023 0.28% and YTD 2026 0.96%, with pills NI($M) $89 and $398 and an arrow labelled 89% CAGR. Grey horizontal divider lines separate the sections. Small logos at bottom left: a blue E mark and a green seal icon.
Slide 19
Transformation is Driving Meaningful Improvement in Financial Performance
Actual
Management Forecast
Efficiency Ratio (1)
'26 YTD: 53%
85%
65%
61%
53%
51%
51%
2023 2024 2025 2026 2027 2028
Net Interest Margin
'26 YTD: 2.62%
2.05%
2.34%
2.62%
2.65%
2.74%
2.78%
2023 2024 2025 2026 2027 2028
ROAA (1)
'26 YTD: 0.96%
0.28%
0.59%
0.71%
0.94%
0.98%
1.00%
2023 2024 2025 2026 2027 2028
Loans HFI ($B)
17% CAGR
7% CAGR
$26.2
$29.5
$35.9
$38.6
$41.9
$43.5
2023 2024 2025 2026 2027 2028
Deposits ($B)
16% CAGR
7% CAGR
$27.2
$31.6
$36.8
$40.2
$43.8
$45.7
2023 2024 2025 2026 2027 2028
Net Income to Common ($M) (1)
'26 YTD: $199
72% CAGR
23% CAGR
$89
$186
$262
$394
$438
$486
2023 2024 2025 2026 2027 2028
Source: EverBank management; S&P Global Market Intelligence
1. Not adjusted for one-time costs
19
Visuals: Six vertical bar charts with no gridlines or y-axes, only a faint baseline under each and year labels 2023 to 2028 beneath. Bars for 2023-2025 are dark navy (Actual); bars for 2026-2028 are bright blue (Management Forecast) in every chart except Efficiency Ratio, where 2026-2028 are also bright blue. Legend: navy square 'Actual', blue square 'Management Forecast'. Top row: Efficiency Ratio 85%, 65%, 61%, 53%, 51%, 51% (decreasing bars); Net Interest Margin 2.05%, 2.34%, 2.62%, 2.65%, 2.74%, 2.78%; ROAA 0.28%, 0.59%, 0.71%, 0.94%, 0.98%, 1.00%. Each top-row panel has a small dashed blue-outlined callout box under the header: '26 YTD: 53%, '26 YTD: 2.62%, '26 YTD: 0.96%. Bottom row: Loans HFI ($B) 26.2, 29.5, 35.9, 38.6, 41.9, 43.5 with a blue arrow labelled 17% CAGR over 2023-2025 and another labelled 7% CAGR over 2025-2028; Deposits ($B) 27.2, 31.6, 36.8, 40.2, 43.8, 45.7 with arrows 16% CAGR and 7% CAGR; Net Income to Common ($M) 89, 186, 262, 394, 438, 486 with arrows 72% CAGR and 23% CAGR and a dashed callout '26 YTD: $199. CAGR arrows are thin blue lines with arrowheads, angled upward, and their labels are bold blue italic-looking text rotated along the slope. Footer-left has the EverBank 'E' logo in blue, a thin vertical divider, and a green circular seal icon.
Slide 20
Financial Rationale
20
Visuals: Full-bleed abstract background image (1536x864 px) of flowing translucent ribbon waves. Blue ribbons (royal blue #0B6BD6 to pale sky blue #BBD2F0) sweep from the top-left corner and taper down toward the centre-right, with fine parallel hairlines at the left edge. They fade into white around the slide centre (x about 50%, y about 55%). Green ribbons (deep green #2E9A3E to pale mint #DDEEDD) emerge from the centre and sweep to the bottom-right corner, with thin white curved lines. Large pale grey-white arcs curve through the right side. The top-right and bottom-left are near-white open space.
Slide 21
Key Financial Assumptions
Standalone earnings:
WaFd: Consensus earnings estimates through 2027(1)
EverBank: Management forecast through 2028, as reflected on slide 19
Cost savings:
$135mm annual run-rate pre-tax cost savings (~11% of the combined NIX); grown 3% annually
40% phase-in during 2027, 100% phase-in by 2H 2028
Revenue synergies:
Not modeled in pro forma financial metrics; significant opportunities identified, including insurance and wealth(2)
One-time costs:
$280mm pre-tax (for illustrative purposes, fully reflected in pro forma capital at closing)
Credit mark:
$313mm (1.55% of WaFd’s projected gross loans at closing, 1.45x WaFd’s loan loss reserve at close)
Fair value marks / on WaFd:
($601mm) pre-tax loan mark accreted 10 years using straight-line method
($145mm) pre-tax securities mark accreted 4.5 years using straight-line method
$29mm pre-tax fixed assets mark amortized 40 years using straight-line method
$15mm pre-tax time deposits mark amortized 1 year using straight-line method
$3mm pre-tax other borrowings mark amortized 2 years using straight-line method
$105mm preferred equity mark
CDI:
Core deposit intangible of $357mm, 2.8% of WaFd’s core deposits, amortized over 10 years using sum-of-years digits
Other:
Company plans to enter into hedges to manage interest rate risk between announce and close
Outstanding EverBank options rolled into economic equivalent for the pro forma company
Pro forma metrics reflect illustrative January 1, 2027 closing date
Source: Company filings; FactSet; S&P Global Market Intelligence
Notes:
1. Based on mean analyst consensus estimates as of September 4, 2026; 2. Excludes TIAA depositors which, by agreement, may not be solicited for wealth management services
21
Visuals: Eight pale blue (#E4EAFC) label cells, each with a dark navy (#1B2A7A) vertical bar on its right edge. Thin grey horizontal divider lines between rows, extending across the right-hand text area. Blue filled circular bullets before each bullet line. A thin grey horizontal line above the footer. Bottom-left shows two small logos separated by a thin vertical line: a blue stylised 'E' (EverBank) mark and a green circular emblem (WaFd).
Slide 22
Overview of Cost Savings and Integration Timeline
Cost Synergies Schedule ($mm)
Summary of Cost Synergies
Integration Plan
Annualized cost synergies
Realized cost synergies
%
Phased in
$135
$135
$139
$108
$139
$54
40%
100%
2027E
4Q 2027 run-rate
Mid-year 2028E run-rate
Compensation
General & / admin
Technology & / occupancy
$135M
11% of combined / expenses
Defined key leadership roles and / organizational structure to support post- / close execution
Establishment of Integration / Management Office (“IMO”)
Includes senior leaders from both / organizations across operations, / technology, HR, finance, legal & / regulatory, communications, and project / management
Provides clear accountability and / decision-making authority across / integration workstreams prior to close
Enables front-line teams to remain / focused on customers while ensuring / disciplined execution against key / integration milestones
Launched 27 integration workstreams / with designated business owners
Advanced key technology decisions / including core, accounting and HR- / related systems
Management team highly experienced / with M&A integration
Core Conversion and Integration Timeline
Key Milestones
Target close date(1)
Core conversion date
Integration completion target
Q1’27
Q2’27
Q3’27
Q4’27
H1’28
H2’28
Source: EverBank management
Notes:
1. Legal Day 1
22
Visuals: Stacked bar chart of three columns: 2027E has a solid cyan bar $54 (40% bubble) under a dashed-outline light grey box totalling $135; 4Q 2027 run-rate has cyan $108 under a dashed grey box totalling $135; Mid-year 2028E run-rate has a solid cyan $139 bar (100% bubble), total $139. Legend: dashed outline square = annualized, solid cyan square = realized, light blue oval with % = phased in. Donut chart with $135M centre: Compensation (cyan, about 55%), Technology & occupancy (dark navy, about 25%), General & admin (royal blue, about 20%). Timeline: six navy rounded boxes Q1'27 to H2'28 linked by dotted grey connectors; grey label tags with dashed vertical connectors from Target close date to Q1'27, and from Core conversion date and Integration completion target to H1'28. Logos: EverBank/Sterling, U.S. Bancorp, TIAA Bank, UnionBank, TIAA, Umpqua, WaFd, SterlingBank, Luther Burbank. Footer logos: EverBank mark and green WaFd-style mark separated by vertical line.
Slide 23
Strong Financial Profile with an Efficient, Scalable Operating Model
2027E Pro Forma Financials and 2028E Targets
Efficiency Ratio
Noninterest Expense / Assets
Net Interest Margin
55%
51%
45%
~45%
1.65%
1.49%
1.47%
~1.45%
2.83%
2.74%
2.89%
~2.95%
2027
2027
2027 pro forma
2028 target
2027
2027
2027 pro forma
2028 target
2027
2027
2027 pro forma
2028 target
ROAA
ROATCE
Net Income to Common ($mm)
EPS
$3.37
$4.34
0.95%
0.98%
1.10%
~1.15%
10.5%
11.9%
15%+
15%+
$250
$438
$788
$865+
2027
2027
2027 pro forma
2028 target
2027
2027
2027 pro forma
2028 target
2027
2027
2027 pro forma
2028 target
Source: Company filings; EverBank management; FactSet
Notes: Represents fully synergized metrics on a calendar year basis; WaFd standalone based on mean analyst consensus estimates as of September 4, 2026
23
Visuals: Six bar charts, each with four bars and no axes or gridlines: green (first), bright blue (second), and two navy bars (pro forma and 2028 target). Values are printed above the bars. Under each bar is a logo: a green outlined starburst/flower logo (WaFd) for the first bar, a blue stacked-chevron 'E' logo (EverBank) for the second, and for the last two bars both logos separated by a thin navy vertical bar. Efficiency Ratio: 55%, 51%, 45%, ~45%. Noninterest Expense / Assets: 1.65%, 1.49%, 1.47%, ~1.45%. Net Interest Margin: 2.83%, 2.74%, 2.89%, ~2.95%. ROAA: 0.95%, 0.98%, 1.10%, ~1.15%. ROATCE: 10.5%, 11.9%, 15%+, 15%+. Net Income to Common ($mm): $250, $438, $788, $865+. It has an EPS legend with a blue oval marker, and dark blue oval callouts with white text: $3.37 above the first bar and $4.34 above the third bar. Footer left has the EverBank and WaFd logos separated by a vertical line. A thin grey horizontal rule sits above the footer.
Slide 24
Drivers of Earnings Power
Combination Unlocks Earnings Power
Additional Upside Levers
’27E EPS
$3.37
~29%
$4.34
$50
$100
$788
$438
($49)
$250
WaFd ’27E / consensus net / income
EverBank ’27E / net income
Fully phased / in synergies(1)
NII & merger / adjustments(1) (2)
CDI amortization
Pro forma net / income
’27E ROATCE
10.5%
11.9%
15%+
Back-book redeployment — Redeploy low-yielding legacy assets into / higher risk-adjusted return loans
Balance-sheet scale — A larger combined balance sheet expands / underwriting capacity
Portfolio granularity & diversification — Greater loan granularity and / sector diversification reduce concentration risk and create a platform to / expand existing verticals
Up-market capability — Enhanced products and balance-sheet / capabilities enable the combined franchise to serve larger, more / sophisticated clients
Funding optimization — Flexibility to optimize funding mix across / branch and digital channels
Expand insurance income — Cross-selling personal and commercial / insurance across the combined franchise
Wealth cross-sell — WaFd's wealth management offering can be / extended to EverBank’s affluent client base (3)
Capital return optionality — Robust capital generation affords flexibility / for capital return alongside organic reinvestment
Long-term targets: / 15%+ ROATCE / High-single digit core loan growth
Source: Company filings; EverBank management; FactSet; S&P Global Market Intelligence
Notes: Market data as of September 4, 2026; Financial data as of June 30, 2026; WaFd standalone based on mean analyst consensus estimates as of September 4, 2026; Metrics shown on a calendar year basis
1. Reflects after-tax metrics; 2. Includes interest rate mark accretion, AOCI amortization, swap cash flow and cost of cash on the restructuring charge; 3. Excludes TIAA depositors which, by agreement, may not be solicited for wealth management services
24
Visuals: Waterfall chart of 2027E net income in $ millions with six columns on a thin light-grey baseline, no axes or gridlines. Columns: WaFd ’27E consensus net income $250 (cyan bar); EverBank ’27E net income $438 (royal blue floating bar stacked above $250); Fully phased in synergies $100 (light green floating bar); NII & merger adjustments $50 (light green floating bar); CDI amortization ($49) (light pink floating bar); Pro forma net income $788 (cyan bar). Value labels in bold navy sit above each bar. Above the chart, a row labelled ’27E EPS has a dark navy oval pill $3.37 at left, a large royal-blue right-pointing arrow labelled ~29% in white, and a navy oval pill $4.34 at right. Below the chart, a row labelled ’27E ROATCE has navy oval pills 10.5% (under WaFd), 11.9% (under EverBank) and 15%+ (under pro forma). Beneath the pills: a green WaFd starburst logo under the 10.5% pill, a blue EverBank logo under the 11.9% pill, and both logos separated by a vertical bar under the 15%+ pill. Right panel has seven-plus bullets with royal-blue round bullet dots. Small WaFd and EverBank logos with a divider appear in the footer bottom-left.
Slide 25
Strong Liquidity Position and Capital Provides for Balance Sheet Flexibility
Balance Sheet Position
Capital Framework
Well Capitalized Balance Sheet at Close
✓ Neutral balance sheet positioning
✓ Multiple sources of readily available liquidity
✓ $15bn of residential mortgages running off providing incremental liquidity optionality over time
✓ Conservative liquidity management maintaining substantial capacity to support future growth
✓ 82% of deposits are FDIC-insured or collateralized, supporting a stable and resilient funding base
✓ Meaningful profitability drives excess capital generation, creating optionality for growth and returns
✓ Capital management priorities include supporting organic growth, maintaining dividend payout ratio and prudent share buybacks
✓ Preliminary estimate of capital impact with Basel III endgame proposal results in 125–140bps of additional capital
TCE / TA
7.0%
CET1
9.8%
>10% CET1
1–2 quarters
post-close
Tier 1 Capital
11.2%
Total Capital
12.6%
Tier 1 Leverage
8.1%
Near to Medium Term Balance Sheet Targets
~20%
Cash + Securities / Assets
Mid 90%
Loan / Deposit Ratio
25–35%
Dividend Payout Ratio
10%+
CET1
8.0%+
Tier 1 Leverage
Source: EverBank management; FactSet; S&P Global Market Intelligence
Note: For illustrative purposes, assumes all one-time costs are reflected in capital ratios at close
25
Visuals: Horizontal bar chart (no axis labels, thin grey vertical axis line) with five dark navy bars: TCE / TA 7.0%, CET1 9.8%, Tier 1 Capital 11.2%, Total Capital 12.6%, Tier 1 Leverage 8.1%. Value labels sit to the right of the bars. A callout box with a navy outline and pale fill, reading '>10% CET1 1–2 quarters post-close', sits beside the CET1 bar. Five pale-blue cards with drop shadows hold the targets. Navy check marks mark each bullet. Footer shows two small logos: a blue stylised 'E' mark and a green circular emblem, separated by a thin vertical line.
Slides 26 to 43 continue in the full text file.
Download this deck
The hosted PDF of every library deck is free for readers of the SlideDeck Co newsletter. Join with your email and the viewer and download appear here.
Building a pitch deck of your own? The SlideDeck Co Startup Deck is a slide library with a worked investor pitch and financial model.