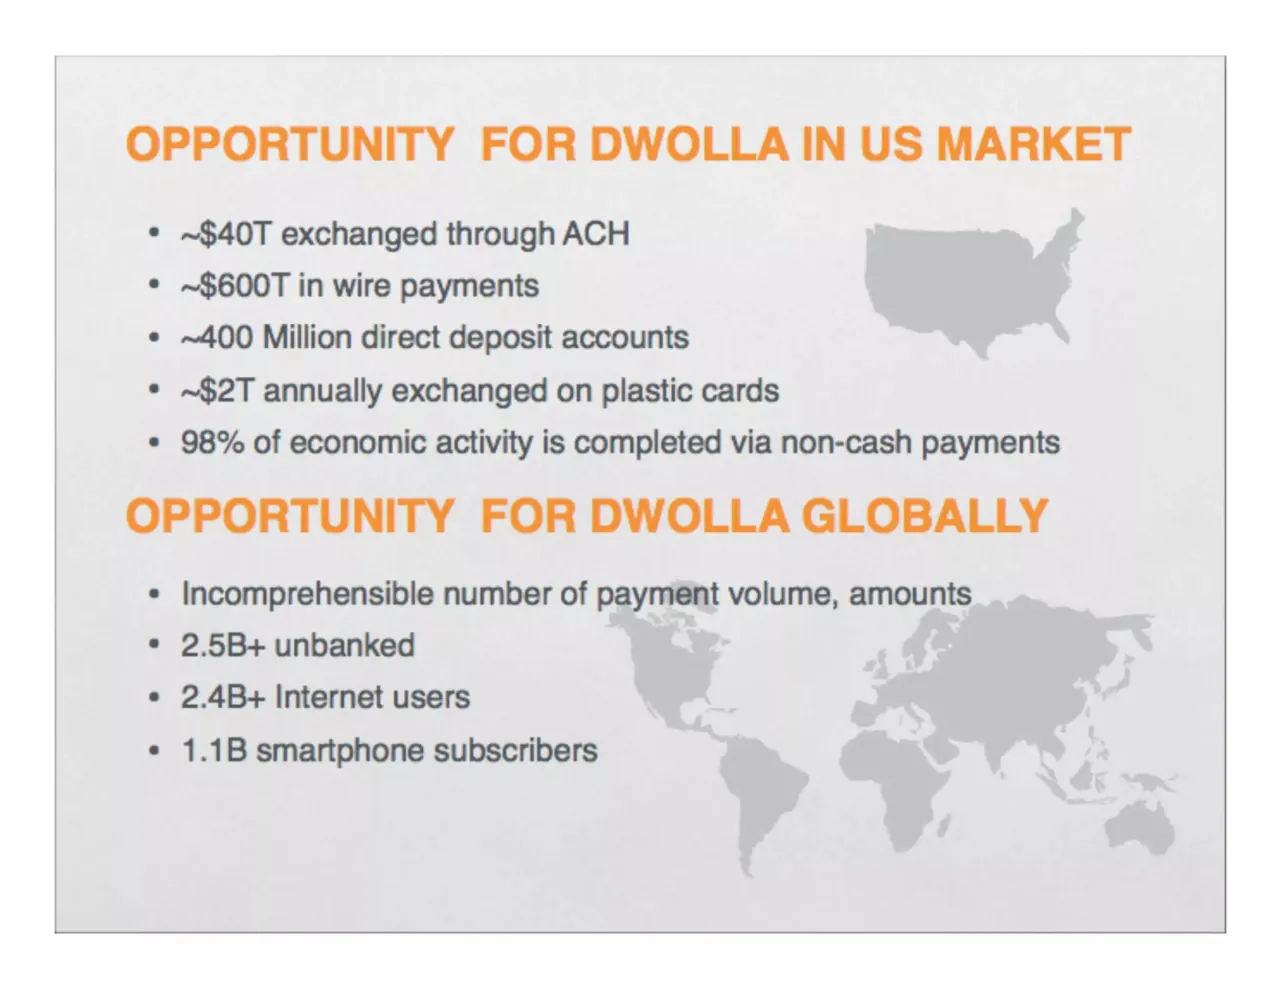
The deck opens with a title slide and a one-line solution statement: Dwolla lets anything connected to the internet move money quickly, safely and cheaply. It then shows growth through a list of use cases, from individuals and schools to banks and developers, before introducing the founders and the origin of the company in the credit card fee problem. The middle sections build the case in order. A diagram shows how card payments flow and where fees accumulate. A list of problems with existing payment rails is grouped under cost, speed, fraud and bank dependence. A diagram of the Dwolla flow includes a real-time settlement step. Later slides cover the end-to-end product, the technology, the network's advantages, and the market opportunity in the US and globally. The deck closes with a 2013 hiring and expansion plan, a references slide and a closing title.
Full text of the slides (18 slides)
Every slide's words and a description of its charts and images, so the deck can be searched and rebuilt. Also available as Markdown.
Slide 1
DWOLLA
the best way to move money
Visuals: Logo: an orange stylised S-shaped ribbon mark (Dwolla logo mark) to the left of the wordmark, with a darker orange shaded fold at its lower-left end and two pale highlight ovals on its upper-middle body. Behind the grey background is a faint, low-contrast pattern of monochrome pictogram icons in rows (including a shirt, a cloud, a cup, a martini glass, a car, a shopping cart, a map pin, cutlery, a dumbbell, a wine glass, a bottle, a bank building, a music note, a trash bin, and a bell-like shape), tinted only slightly darker than the grey background.
Slide 2
HOW WE SOLVE THE PROBLEM
Dwolla allows anything connected to the internet to move money quickly, safely, and at low cost.
Visuals: Diagram: a circular cycle of four icons connected by thin light grey curved arrows. Top icon: solid dark grey person silhouette (bust) #45494F at about x 44%, y 48%. Right icon: solid dark grey bank building with a pediment and four columns, at about x 56%, y 74%. Bottom-left icon: solid dark grey pair of office buildings with window grids, at about x 32%, y 74%. Centre icon: solid dark grey gear/cog with a hollow centre, at about x 44%, y 66%. Arrows: four curved light grey (#B9BBBF) arrows with small open arrowheads. One arrow runs from the person icon down-left to the buildings icon. One runs from the buildings icon up to the person icon. One runs from the person icon down-right to the bank icon. One runs from the bank icon up-left to the person icon. Two arrows along the bottom run between the buildings and bank icons in opposite directions. The gear sits in the centre of the cycle with no arrow connecting to it. No photographs, logos or charts.
Slide 3
GROWING RAPIDLY BECAUSE OF MANY USE CASES
Individuals »
I use Dwolla to pay my friends / back for lunch
Government »
Our State uses Dwolla to accept / tax stamp payments.
Schools »
Our school district uses Dwolla to / collect lunch money from parents.
Businesses »
My business uses Dwolla to / payout service providers
Financial Institutions »
Our Bank uses Dwolla to offer its / 'pay anyone' technology to our / customers.
Developers »
I built Dwolla into my web application.
Non-profits »
My church uses Dwolla for tithing.
Visuals: Diagram: seven circular portrait photos, each with a bold label ending in a double chevron (») and a short description, plus four solid dark grey (#3B3E44) flat pictograms at the centre: a single person silhouette above the centre (top), a gear/cog in the middle, a pair of office buildings at lower left, and a classical bank building with columns at lower right. Curved grey arrows (#B5B7BB, about 0.3% stroke) run between the centre icons and the nodes: an outer arc from the buildings up to Government and another from the bank up to Schools, inner arcs from the buildings to the person and from the bank to the person, and two arrows along the bottom linking buildings and bank in opposite directions. Photos: Individuals, bearded man with light brown hair and plaid shirt against a pale background; Government, older man with grey hair, dark suit and red tie against a black background; Schools, smiling man with short dark hair and open collar against a green background; Businesses, woman in a dark cap against a blurred olive background; Financial Institutions, smiling man in a dark suit against a light grey background; Developers, man with dark hair and glasses against a white background; Non-profits, bald man with glasses against a bookshelf background. Photos are circular crops with a thin light grey rim and soft shadow, lit evenly from the front.
Slide 4
HOW DID WE GET HERE?
Dwolla was started as a direct result of a problem encountered by its founder: the pain of paying $50,000+ a year in credit card fees. In 2008 Ben Milne set out to fix the problem and Dwolla was born.
Ben Milne, Founder & CEO
Started his first manufacturing company at 18, bootstrapped the company to 1M + in revenue with operations in the US and Asia.
Sold the company to concentrate on building the Dwolla network.
Leads overall company vision, technology, product strategy and marketing.
Charise Flynn, COO
Graduated magna cum laude from Simpson College with degrees in Philosophy and Religion.
Started career in real estate development by building and managing over $100MM in real estate assets in less than five years.
Built consulting company, c.Results, which focused on working with early stage companies/founders.
Joined Dwolla in 2010 and leads operations including legal, finance, business development, human resources, and customer support.
Visuals: Two black-and-white circular portrait photographs, each boxed as a circle with a soft drop shadow. Top photo: head-and-shoulders of a bearded man with thin-framed glasses, wearing a dark crew-neck T-shirt printed with the word DWOLLA in white block letters; plain mid-grey background; soft even front lighting; framing shows head and upper chest, cropped at the circle edge. Bottom photo: head-and-shoulders of a woman with shoulder-length wavy light-brown hair, dark top, looking directly at camera with a neutral expression; mid-grey background; soft front lighting; cropped at the circle edge. Both photos are desaturated to greyscale. No charts, tables or other graphics.
Slide 5
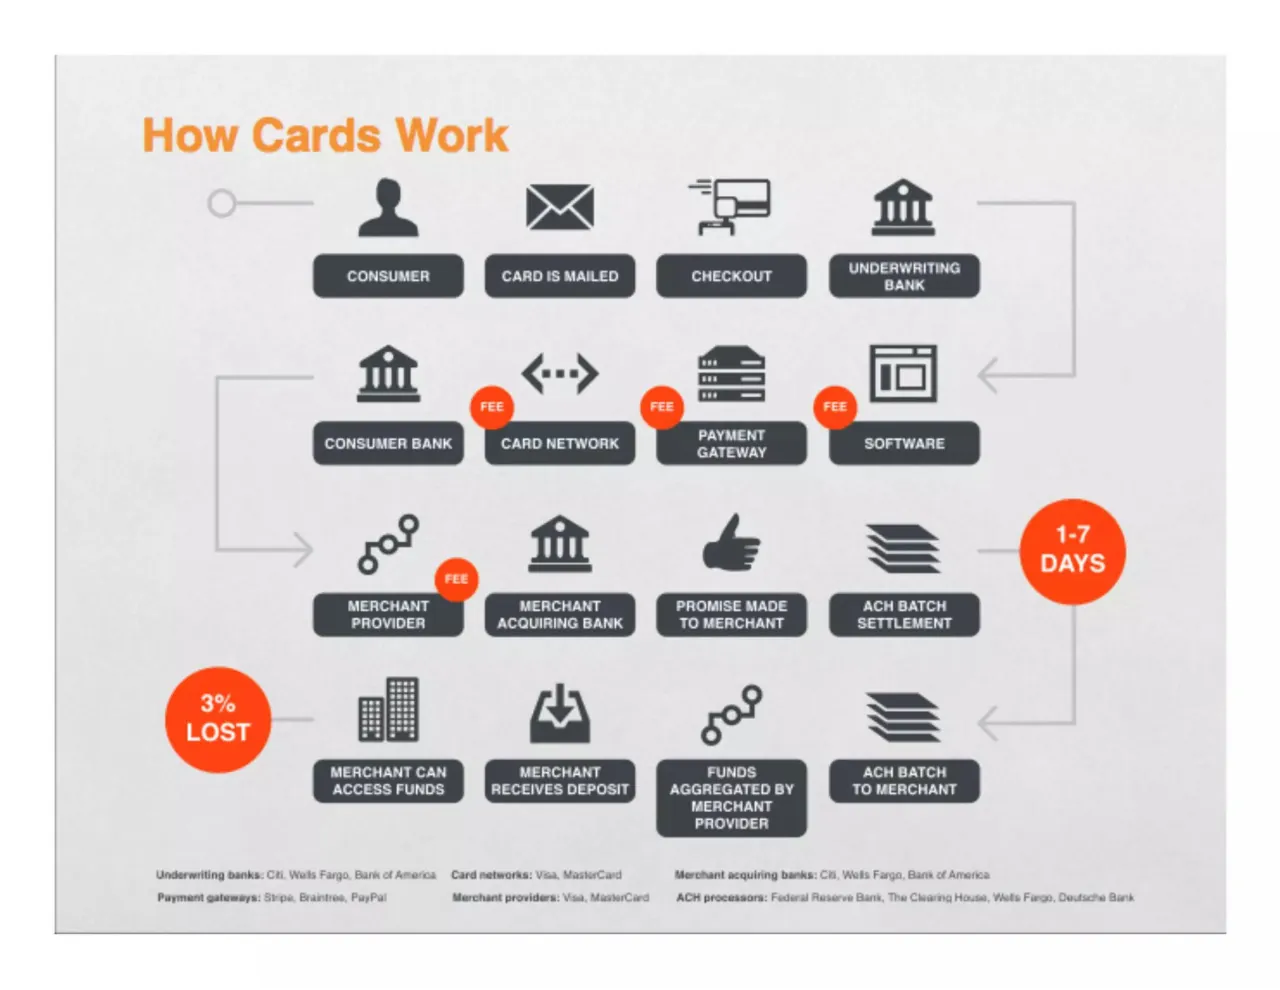
How Cards Work
CONSUMER
CARD IS MAILED
CHECKOUT
UNDERWRITING BANK
CONSUMER BANK
CARD NETWORK
FEE
PAYMENT GATEWAY
FEE
SOFTWARE
FEE
MERCHANT PROVIDER
FEE
MERCHANT ACQUIRING BANK
PROMISE MADE TO MERCHANT
ACH BATCH SETTLEMENT
1-7 DAYS
3% LOST
MERCHANT CAN ACCESS FUNDS
MERCHANT RECEIVES DEPOSIT
FUNDS AGGREGATED BY MERCHANT PROVIDER
ACH BATCH TO MERCHANT
Underwriting banks: Citi, Wells Fargo, Bank of America
Card networks: Visa, MasterCard
Merchant acquiring banks: Citi, Wells Fargo, Bank of America
Payment gateways: Stripe, Braintree, PayPal
Merchant providers: Visa, MasterCard
ACH processors: Federal Reserve Bank, The Clearing House, Wells Fargo, Deutsche Bank
Visuals: Process flow diagram with 16 dark charcoal rounded rectangles arranged in four rows, each with a dark charcoal flat pictogram icon above it. Row 1 left to right: CONSUMER (person silhouette), CARD IS MAILED (envelope), CHECKOUT (card on a screen with motion lines), UNDERWRITING BANK (classical bank building). Row 2 right to left arrangement as read: CONSUMER BANK (bank building), CARD NETWORK (left-right double-headed arrow with dashed centre), PAYMENT GATEWAY (server rack), SOFTWARE (browser window with panels). Row 3: MERCHANT PROVIDER (node-and-link graph), MERCHANT ACQUIRING BANK (bank building), PROMISE MADE TO MERCHANT (thumbs-up hand), ACH BATCH SETTLEMENT (stacked layers). Row 4: MERCHANT CAN ACCESS FUNDS (two office towers), MERCHANT RECEIVES DEPOSIT (tray with downward arrow), FUNDS AGGREGATED BY MERCHANT PROVIDER (node-and-link graph), ACH BATCH TO MERCHANT (stacked layers). Four red-orange circular FEE badges with white bold text sit on the corners of CARD NETWORK, PAYMENT GATEWAY, SOFTWARE and MERCHANT PROVIDER. Two large red-orange circles: 1-7 DAYS at right of row 3 and 3% LOST at left of row 4. Connectors are thin mid-grey (#C4C4C4) lines about 2px with open arrowheads: a hollow circle start at row 1 left, a bracket from row 1 right down to row 2 right with arrow pointing left, a bracket from row 2 left down to row 3 left with arrow pointing right, a line from row 3 right to the 1-7 DAYS circle, a bracket from that circle down to row 4 right with arrow pointing left, and a line from the 3% LOST circle to row 4 left. Footnote text is in small sans-serif, bold labels followed by regular lists. No photographs.
Slide 6
THE PROBLEM WITH PAYMENTS
EXPENSIVE (“ASSET-HEAVY”)
Merchants shell out ~$40-$50 billion a year to process credit/debit card payments. Does not include hardware, hidden fees, etc.
Innovation can only happen on top of the network, which increases cost rather than reducing cost.
Legacy payment options such as ACH and check are layered with administrative and operational costs that businesses, individuals, financial institutions and governments have to bear the cost of.
Micro-transactions are cost-prohibitive.
SLOW/ACCESSIBILITY
Check and ACH can take 3-15 days to get from senders’ to receivers’ bank account.
Dependent on bank holidays, ATM availability
Slide 7
THE PROBLEM WITH PAYMENTS
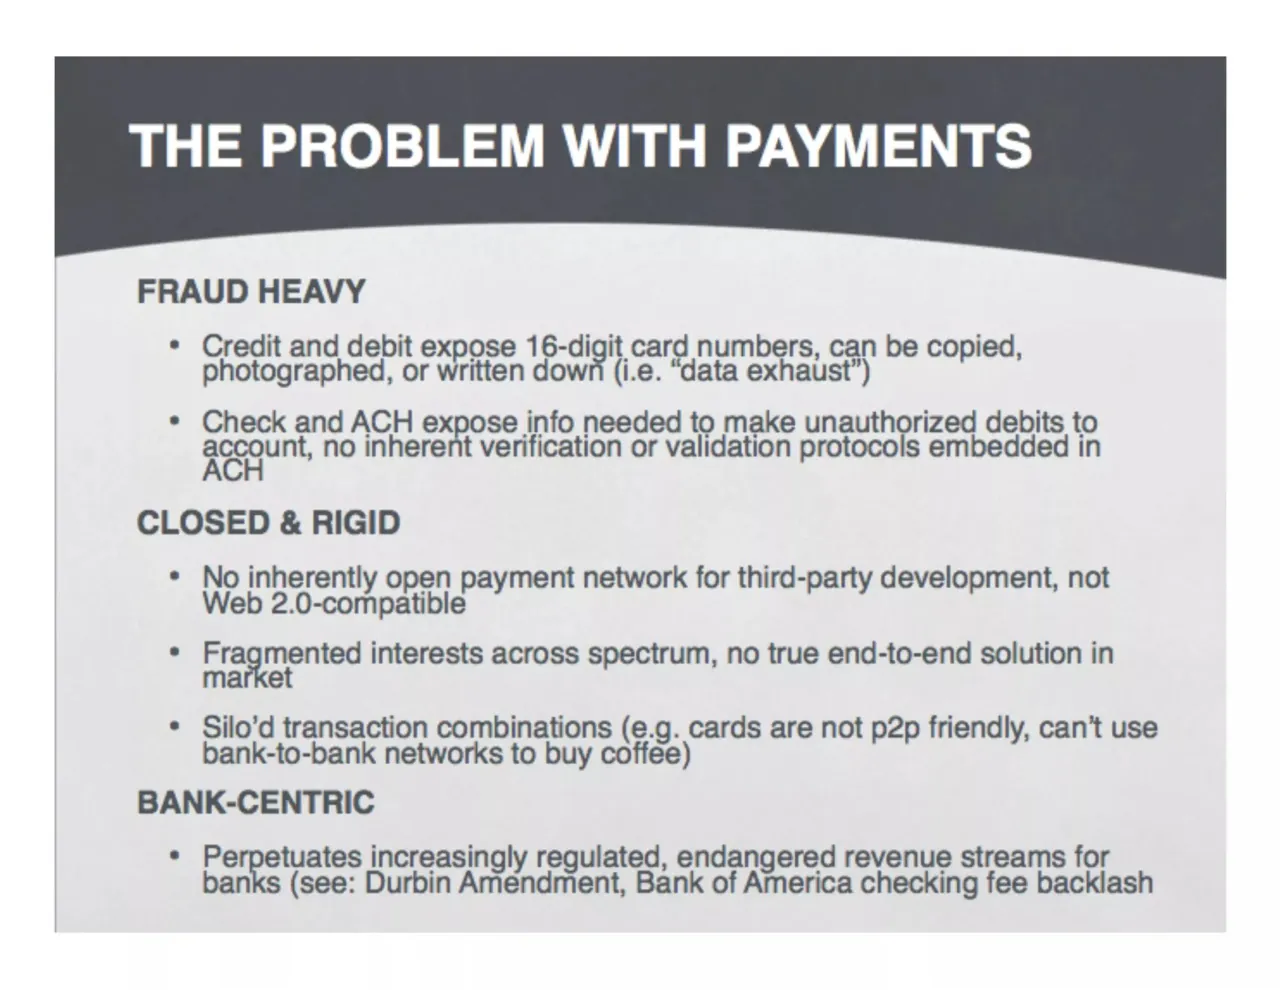
FRAUD HEAVY
Credit and debit expose 16-digit card numbers, can be copied, photographed, or written down (i.e. “data exhaust”)
Check and ACH expose info needed to make unauthorized debits to account, no inherent verification or validation protocols embedded in ACH
CLOSED & RIGID
No inherently open payment network for third-party development, not Web 2.0-compatible
Fragmented interests across spectrum, no true end-to-end solution in market
Silo’d transaction combinations (e.g. cards are not p2p friendly, can’t use bank-to-bank networks to buy coffee)
BANK-CENTRIC
Perpetuates increasingly regulated, endangered revenue streams for banks (see: Durbin Amendment, Bank of America checking fee backlash
Slide 8
And more...
Slide 9
How Dwolla Works
CONSUMER OR MERCHANT
PAYMENT THROUGH SOFTWARE (DWOLLA)
BANK
<1
SECOND
PAYMENT NETWORK (DWOLLA)
REAL-TIME STREAMING SETTLEMENT (FISYNC)
RECEIVE PAYMENT
ACCESS FUNDS
Visuals: Diagram of a process loop with nine cells. Row 1: a dark grey icon of a person beside two office buildings, labelled CONSUMER OR MERCHANT; an icon of a monitor and phone with the orange Dwolla S mark, labelled PAYMENT THROUGH SOFTWARE (DWOLLA); a dark grey bank building icon, labelled BANK. Row 2: a solid green circle reading '<1' over 'SECOND' in white bold type; an orange Dwolla S mark, labelled PAYMENT NETWORK (DWOLLA); a dark grey circular-arrow icon with an orange lightning bolt, labelled REAL-TIME STREAMING SETTLEMENT (FISYNC). Row 3: a dark grey inbox-with-down-arrow icon, labelled RECEIVE PAYMENT; a dark grey dollar sign, labelled ACCESS FUNDS; a solid orange circle containing a white crossed-out credit card icon with no label. Connectors: a light grey open circle at the far left of row 1 with a line to the first icon; a light grey line from the bank cell down the right edge and left into an arrowhead at the row 2 right cell; a light grey line from the left edge of the green circle left, down and right into an arrowhead at the RECEIVE PAYMENT icon; a light grey line from ACCESS FUNDS to the orange circle and from the orange circle to a light grey check-mark circle at the far right of row 3. Stroke about 3 px light grey #C4C4C4. Flat style, no shadows, no photographs.
Slide 10
Product demo...
Slide 11
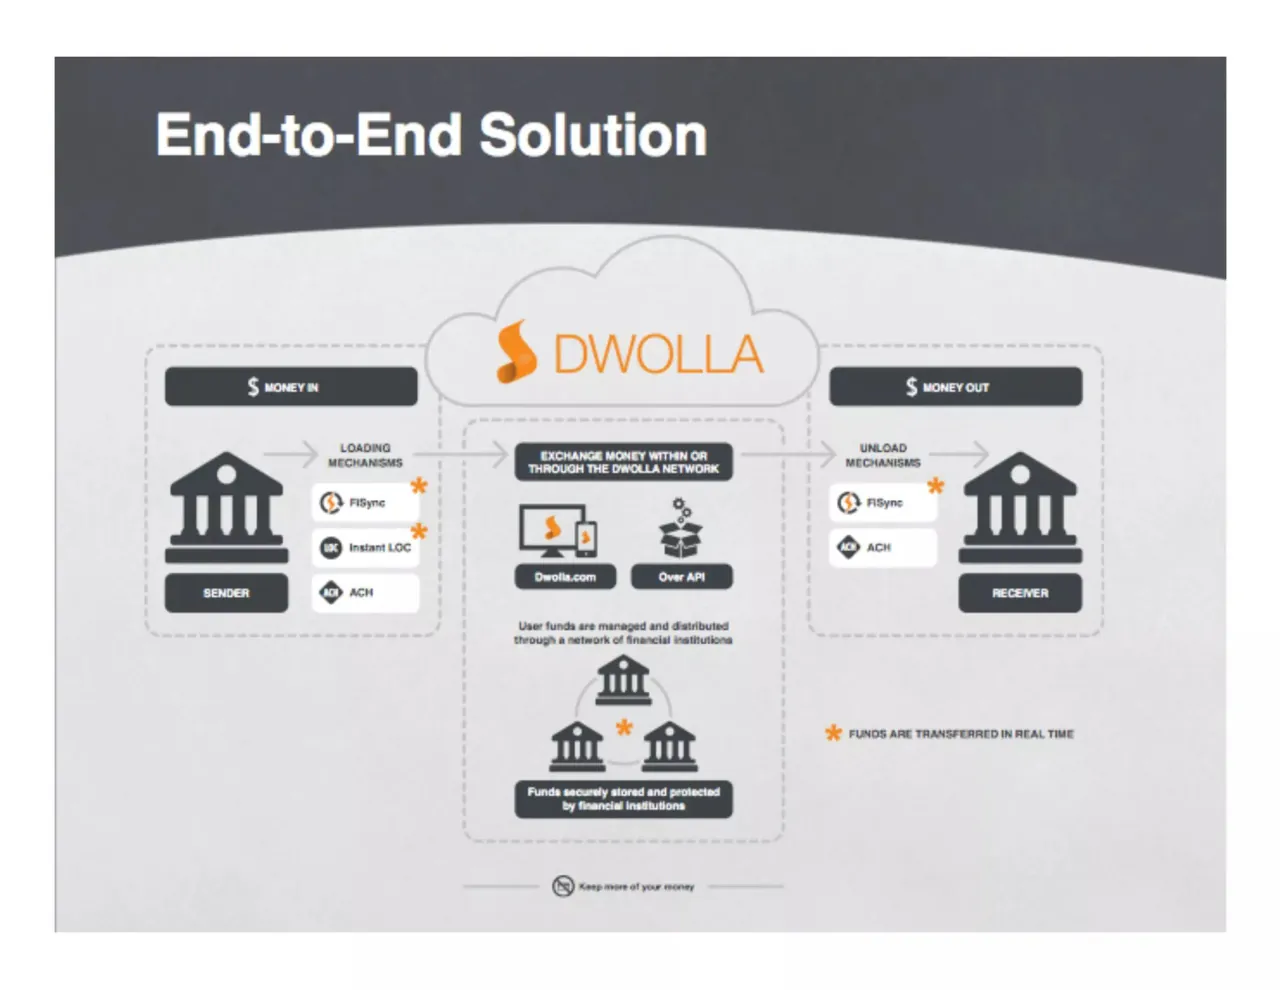
End-to-End Solution / MONEY IN / DWOLLA / MONEY OUT / LOADING MECHANISMS / EXCHANGE MONEY WITHIN OR THROUGH THE DWOLLA NETWORK / UNLOAD MECHANISMS / SENDER / FISync / Instant LOC / ACH / Dwolla.com / Over API / RECEIVER / FISync / ACH / User funds are managed and distributed through a network of financial institutions / * FUNDS ARE TRANSFERRED IN REAL TIME / Funds securely stored and protected by financial institutions / Keep more of your money
Visuals: Diagram. Cloud outline (light grey stroke, white fill) centred at top containing the orange DWOLLA wordmark with orange swoosh logo. Left dashed rounded container labelled by dark pill 'MONEY IN' with dollar icon; contains a bank-building icon above dark pill 'SENDER', arrow to 'LOADING MECHANISMS' label, and three white rounded cards stacked: FISync (with orange asterisk), Instant LOC (with orange asterisk), ACH (no asterisk). Centre dashed container contains dark pill 'EXCHANGE MONEY WITHIN OR THROUGH THE DWOLLA NETWORK', a monitor/phone icon labelled 'Dwolla.com' and a box-with-gears icon labelled 'Over API', text 'User funds are managed and distributed through a network of financial institutions', three bank icons in a circle with an orange asterisk in the middle, and dark pill 'Funds securely stored and protected by financial institutions'. Right dashed container contains dark pill 'MONEY OUT' with dollar icon, arrow from centre to 'UNLOAD MECHANISMS' label, white cards FISync (orange asterisk) and ACH, and a bank icon above dark pill 'RECEIVER'. Grey arrows connect the columns left to right. Orange asterisk and text 'FUNDS ARE TRANSFERRED IN REAL TIME' at right. Bottom centre a thin grey rule, a circular icon and 'Keep more of your money' with rules on either side.
Slide 12
Under the hood
Unique Technology
Consumer (Dwolla branded) Engine.
FiSync (Real Time Gross Settlement - white label) Engine.
End to End fraud control,
Secret Sauce
Secret Sauce
Patents/Pending Patents
Cool, technical sounding stuff goes here
Visuals: None. The slide has no chart, photograph, illustration, icon or logo. It has three flat mid-grey (#868888) rectangles used as placeholder boxes: two 'Secret Sauce' callouts and one large empty box containing the text 'Cool, technical sounding stuff goes here'. The large box holds four bullet points that sit outside its left edge.
Slide 13
THE DWOLLA NETWORK / LOW COST “ASSET-LIGHT” / • Cuts expensive credit card fees out of the equation by bypassing / existing card networks. / • $.25/transaction fee model is cheaper than credit cards or mailing/ / processing check payments. / • Free micro-transactions (under $10) unlock new profit-making / innovations, services, and markets / FAST/ACCESSIBLE / • Faster than mailing a check, pre-loaded funds move in real time / • FiSync Technology is first real-time gross settlement (RTGS) system / in US / • Use with any web-enabled device
Slide 14
THE DWOLLA NETWORK
SAFER & PRIVACY FOCUSED
Guards sensitive financial information, never discloses this data inside transactions or devices.
Privacy innovations, like “Add/Remove Features” revoke access to third-party applications
OPEN-LOOP & END-TO-END
Dwolla API allows distributes network and third-party innovation
With FiSync, Dwolla streamlines payments from user bank account-to-user bank account
Agnostic to payment type (i.e. p2p, b2b, c2b, b2c, g2b, b2g, etc.) or hardware
BANK-FRIENDLY, CONSUMER-CENTRIC
FiSync provides banks and credit unions with dynamic value-added product and services opportunities
Slide 15
OPPORTUNITY FOR DWOLLA IN US MARKET / ~$40T exchanged through ACH / ~$600T in wire payments / ~400 Million direct deposit accounts / ~$2T annually exchanged on plastic cards / 98% of economic activity is completed via non-cash payments / OPPORTUNITY FOR DWOLLA GLOBALLY / Incomprehensible number of payment volume, amounts / 2.5B+ unbanked / 2.4B+ Internet users / 1.1B smartphone subscribers
Visuals: Two flat grey silhouette maps, no labels. (1) Upper right: a map of the contiguous United States with Alaska and Hawaii shown as one silhouette, filled mid-grey (about #BDBDBD), about 19% of slide width, placed at the right of the first bullet list. (2) Lower right: a world map showing North and South America, Europe, Africa, Asia and Australia as one flat silhouette in mid-grey (about #C4C4C4), slightly darker over the landmass shapes, about 49% of slide width, partly behind the second bullet list and overlapping the text 'payment volume, amounts'. No photographs, charts or icons.
Slide 16
2013 Hiring/Expansion Plan
Key Hires:
Product
Marketing
Business Development
Developers
2013 Total team counts:
Leadership: 8
Tech: 29
Community Support: 10
Business Development: 8
Product/Design: 6
Risk/Compliance: 4
Marketing: 3
Misc: 2
Expansion
West Coast office in SF
JAN FEB MAR APR MAY JUN JUL AUG SEP OCT NOV DEC
31
35
46
55
62
70
Visuals: Map: a light grey (#D5D5D8) silhouette of the continental United States, no outline, spanning the upper right of the slide with the Pacific coast at left and the northeast coast at upper right. Three dark charcoal (#3A3F47) map pins with white person icons sit on orange (#F7941D) concentric ripple rings at San Francisco (left), a middle point (about Kansas), and the northeast (New York area). A thin light grey curved line connects the three pins left to right. Timeline: a horizontal orange (#F7941D) line about 3 px thick runs from about 13% to 95% of slide width near the bottom, with orange vertical stems rising to circles above month positions JAN, MAR, MAY, JUL, SEP and NOV. Circles, left to right: 31 (small, dark charcoal #3A3F47 with white outline, JAN), 35 (dark, MAR), 46 (dark, MAY), 55 (dark, JUL), 62 (larger dark, SEP), 70 (largest, light grey #BDBDC0 with white outline, NOV, with bold dark number). Circle size increases with the number. Month labels are set in small light grey (#C8C8CC) bold capitals along the axis. No chart axes or legend.
Slide 17
References
www.kpcb.com/file/kpcb-2012-internet-trends-update
http://www.federalreserve.gov/paymentsystems/fedfunds_ann.htm
https://www.nacha.org/sites/default/files/files/ACH_Rules/2013%20Rules%20Ops/
Year-End%202012.pdf
http://www.un.org/apps/news/story.asp?NewsID=43424&Cr=digital
+divide&Cr1#.UX_AdCtARy4
http://www.paymentssource.com/statistics/
Visuals: none (decorative curved dark grey header band only; no photograph, chart, icon or logo)
Slide 18
DWOLLA.COM
The best way to move money
Visuals: A white circular 'no' (prohibition) sign with a diagonal slash over a stylised credit card icon (rectangle with stripe), positioned left of the tagline, about 6% of slide width and 11% of slide height. No photograph or chart. The grey field has a faint soft texture and subtle vignette lighting from the upper centre.